Heating, Ventilation, and Air Conditioning (HVAC) contractor insurance can help you stay prepared when a service call does not go as planned. You work with electrical wiring, refrigerants, and expensive equipment, so even a small mistake could lead to costly property damage. That is why insurance for HVAC contractors may include more than one type of coverage. Infinity Insurance Agency, Inc. (IIA) makes shopping for HVAC business insurance easier by helping you compare options based on your services, tools, vehicles and job site risks. We can also help you get the proof of insurance you may need before starting a project.
Call IIA at 1-855-478-3705 for a quote or get an estimate online today.
Compare HVAC contractor insurance quotes for the coverage you need
A self-employed residential technician may have different coverage needs than a commercial contractor with several crews, service vans and large projects.
HVAC insurance quotes may be based on:
- The type of work you perform, including repairs, installations, maintenance, ductwork or refrigeration
- Whether you work in residential, commercial or new construction settings
- Your annual revenue, payroll and number of employees
- The vehicles you use for work
- The value of your tools and equipment
- Your years in business and claims history
- Your selected coverage limits and deductibles
Emergency calls, peak seasons and large project cycles can change your coverage needs. IIA can help you compare options from multiple carriers instead of offering a one-size-fits-all policy. Get an estimate online or call an agent to discuss your business and budget.
What does general liability insurance for HVAC contractors cover?
Commercial general liability insurance may help pay for covered third-party bodily injury and property damage claims connected to your HVAC business. It may help when your work accidentally injures someone or damages property that does not belong to your business.
HVAC liability insurance may apply in situations such as:
- A condensation line or plumbing connection leaks after an installation and damages a customer’s walls, ceiling or flooring.
- A technician accidentally cuts electrical wiring or a refrigerant line, leading to system failure or property damage.
- A faulty connection causes a leak, overheating or damage to nearby equipment.
- A customer or tenant slips on water, debris or tools left near the work area.
- A ladder, tool or HVAC component damages vents, ductwork, ceilings or finished surfaces.
- An improperly installed unit causes moisture buildup or indoor air quality concerns that require remediation.
- Debris or materials from a job site damage nearby property or a customer’s belongings.
HVAC contractor liability insurance is often part of a broader coverage package. Commercial clients, general contractors, property managers and homeowner’s associations may request proof of liability coverage for large projects or ongoing service agreements.
Coverage for completed operations, damage related to installed equipment or certain faulty workmanship claims depends on the policy. Some options may be available through endorsements or separate coverage. Review the terms, limits and exclusions with an agent so you understand what may and may not be covered.
HVAC business insurance coverage options beyond general liability
General liability is an important starting point, but it may not address every risk your company faces. Depending on your services and business structure, your coverage package may include:
- Business owner’s policy: A Business Owner’s Policy, or BOP, commonly combines general liability and commercial property coverage. It may be useful if you operate an office, shop or storage space. Bundling these coverages may be more cost-effective for some small HVAC businesses than purchasing them separately.
- Workers’ compensation: This coverage may help pay medical expenses and a portion of lost wages when an employee experiences a covered work-related injury or illness. Requirements vary by state, the number of employees and other factors.
- Commercial auto insurance: A personal auto policy may exclude or limit coverage for business use. Commercial auto insurance may cover service vans, pickup trucks and other vehicles used to transport employees, parts, tools and HVAC units.
- Tools and equipment coverage: Also called inland marine coverage, it may cover items such as gauges, recovery machines, vacuum pumps and specialized tools while they are in transit, stored in a work vehicle or located at a job site, subject to policy terms.
- Professional liability insurance: Also known as errors and omissions insurance, this coverage may apply to claims involving professional mistakes, system-sizing errors, improper recommendations or other covered service failures.
- Contractor’s equipment or installation coverage: Depending on the policy, this may cover certain materials, HVAC units and work in progress before installation is complete.
- Commercial umbrella insurance: This coverage may provide additional liability limits after the limits of an underlying covered policy have been reached.
A solo repair technician may need a simpler setup than a full-service company with employees, multiple vehicles, commercial projects and expensive equipment.
Who needs HVAC contractor insurance?
Coverage may be appropriate for:
- Self-employed HVAC technicians and sole proprietors
- HVAC subcontractors
- Residential repair, maintenance and tune-up providers
- Commercial HVAC contractors
- New construction and retrofit specialists
- Emergency and 24/7 service providers
- Companies with multiple crews and service vehicles
- Refrigeration and specialty HVAC trades
- Furnace, air conditioning and heat pump technicians
- Ductwork, ventilation and indoor air quality specialists
Requirements vary by state and municipality. Your location, license, and work may determine whether you must carry specific coverage or limits. A general contractor, commercial client, property manager or Homeowner’s Association (HOA) may also request a certificate of insurance before work begins. A Certificate of Insurance, or COI, summarizes active coverage and limits. It is commonly requested for commercial contracts, subcontractor work, and property management jobs.
HVAC contractor insurance for equipment and jobsite risks
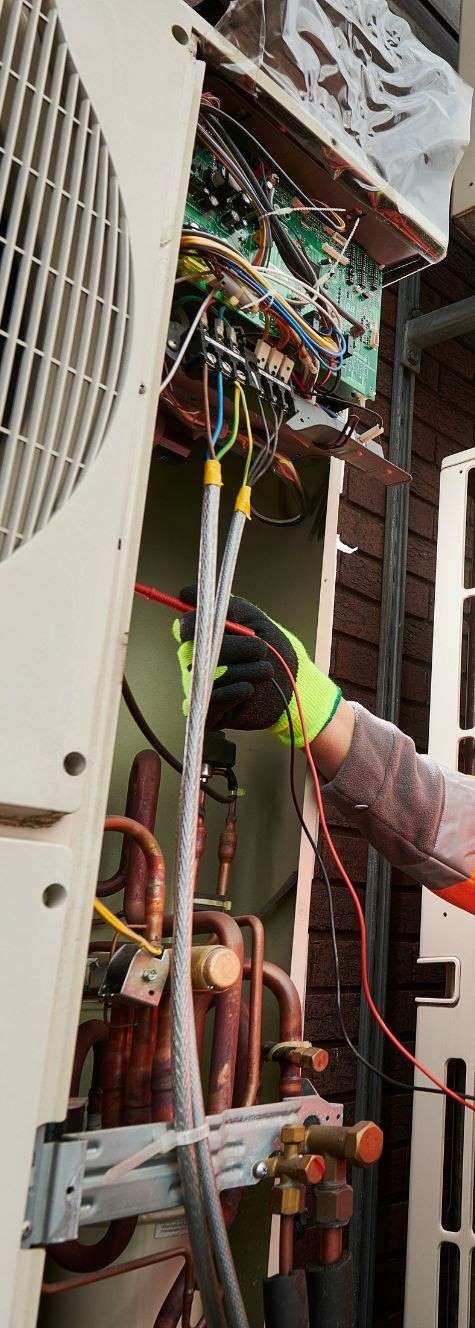
A service call can involve electrical components, water lines, refrigerants, heavy equipment and tight spaces. A wiring mistake could damage a system, a clogged condensate line could cause water damage, and a tool in a walkway could cause a fall.
Your business may also face:
- Accidental damage to walls, ceilings, ducts or nearby property
- Theft of tools or equipment from a van, truck or job site
- Damage while transporting parts, tools or HVAC units
- Injuries connected to work in attics, confined spaces, rooftops or active construction areas
- Refrigerant leaks or environmental exposure concerns
- Loss involving equipment left at a job site
- Contract delays when proof of insurance is unavailable
General liability usually does not cover theft of your own tools. Tools and equipment coverage may be needed. Commercial auto may apply to covered vehicle accidents, while other policies may address liability claims or work in progress.
A solo technician performing tune-ups may have fewer exposures than a company installing commercial refrigeration systems. Seasonal demand and emergency calls can also change how often vehicles and equipment are used.
HVAC insurance cost: What affects your rate?
HVAC insurance cost varies by operation. A part-time residential technician with one vehicle presents a different risk profile than a commercial company with multiple crews and high-value projects.
Carriers may consider:
- The type and complexity of your HVAC work
- Residential, commercial or new construction services
- Refrigeration, gas line or other specialized work
- Business location and local requirements
- Years of professional experience
- Number of employees, payroll and annual revenue
- Service vans, trucks and other work vehicles
- The value of recovery machines, gauges, pumps and other equipment
- Previous property damage, auto or liability claims
- Coverage limits and deductibles
- Full-time, part-time, seasonal or project-based operations
Searching for cheap HVAC insurance may lead you to a low premium, but price alone does not show whether a policy fits your business. Compare liability limits, equipment limits, deductibles, exclusions and available endorsements. A low-cost option could leave important gaps if your company handles expensive systems or jobs with a higher chance of property damage.
Some carriers may accommodate seasonal workloads or changing project demands. An IIA agent can help you compare pricing and coverage features.
Get A Commercial Auto Insurance Quote
What information do you need for HVAC insurance quotes?
Getting a quote can be straightforward when you have a few business details ready. You may be asked for:
- Your business name and contact information
- The types of HVAC work and services you perform
- Whether you handle residential, commercial or new construction projects
- Details about refrigeration, ductwork, indoor air quality or gas line services
- Annual revenue, payroll and employee count
- Years in business and professional experience
- Claims history
- Information about service vans, trucks and other work vehicles
- The types and estimated value of your tools and equipment
- Requested coverage limits
- Whether your operation is full-time, part-time, seasonal or project-based
- Licensing information, when applicable
After a short application, you can compare coverage and pricing. Once a policy is bound and payment is processed, you may receive a COI quickly, depending on the carrier and application.
Accurate details help carriers provide relevant HVAC insurance quotes. Be clear about commercial installations and specialized work involving refrigerants or gas lines.
Get A Commercial Auto Insurance Quote
Why choose IIA for HVAC contractor insurance
IIA helps you compare coverage for real-world HVAC operations, from residential furnace repairs to commercial rooftop work. With IIA, you can:
Compare rates and coverage options from multiple carriers
Work with experienced agents who understand HVAC business risks
Get help in English or Spanish from bilingual agents
Explore flexible payment options
Review coverage for a solo operation, growing crew or full-service commercial company
Discuss options for seasonal demand and fluctuating workloads
Request a COI after coverage is bound and payment is processed, when available
Our team can help you review policies for risks such as property damage, vehicle accidents and equipment theft. You choose the option that fits your services, budget and contracts.
Get insurance quotes for your HVAC business today
The right HVAC contractor insurance should fit the way you work, whether you are a solo technician handling residential service calls or a full-service company managing commercial installations. IIA can help you compare carrier options when you need a COI for a contract, want coverage for employees and vehicles, or are preparing to renew.
Get an estimate online or speak with an insurance agent by calling 1-855-478-3705 today.